Two new hires. Same job. One decision.
When I was 22, I landed my first job out of school. The pay was close to $100,000 a year, which felt like winning the lottery. At the time, my wife and I were in need of a new car as she was borrowing her mom’s. So it was time to go shopping.
I could have afforded something really nice. I didn’t buy it. I’m somewhat frugal by nature, so instead, I went with a two-year-old Toyota Corolla, a former rental, for about $12,000. Paid cash.
A couple of years later, we hired a new grad. Same role, with a similar offer of about $100,000 a year at age 22. He did what most people would consider a reasonable thing with that kind of paycheck. He bought a brand new Tesla Model 3 in 2021. Sticker price? About $50,000.
Neither of us did anything illegal, irresponsible, or even unusual. We just made one decision on one day.
But that one decision is worth roughly $670,000. Let me show you.
The Setup
I ran the numbers on both purchases. To keep it fair, we each put the same $12,000 of cash into our car. The only difference is that he financed the rest. Here are the assumptions:
| Corolla (me) | Model 3 (him) | |
|---|---|---|
| Price | $12,000 | $50,000 |
| Down payment | $12,000 cash | $12,000 |
| Loan | None | $38,000, 4 years, 5% APR |
| Monthly payment | None | $875 |
| Total interest | None | $4,005 |
| Total cash paid | $12,000 | $54,005 |
Then the key assumption. If I’m not making a car payment, I invest that same amount every month into a basic index fund earning 7% a year, a bit below the long-run historical average.
The First Five Years
After five years, the Model 3 has lost about $27,800 of its value to depreciation, and he has paid about $4,000 in interest. Call it $32,000 in real cost. The Corolla cost me about $4,900.
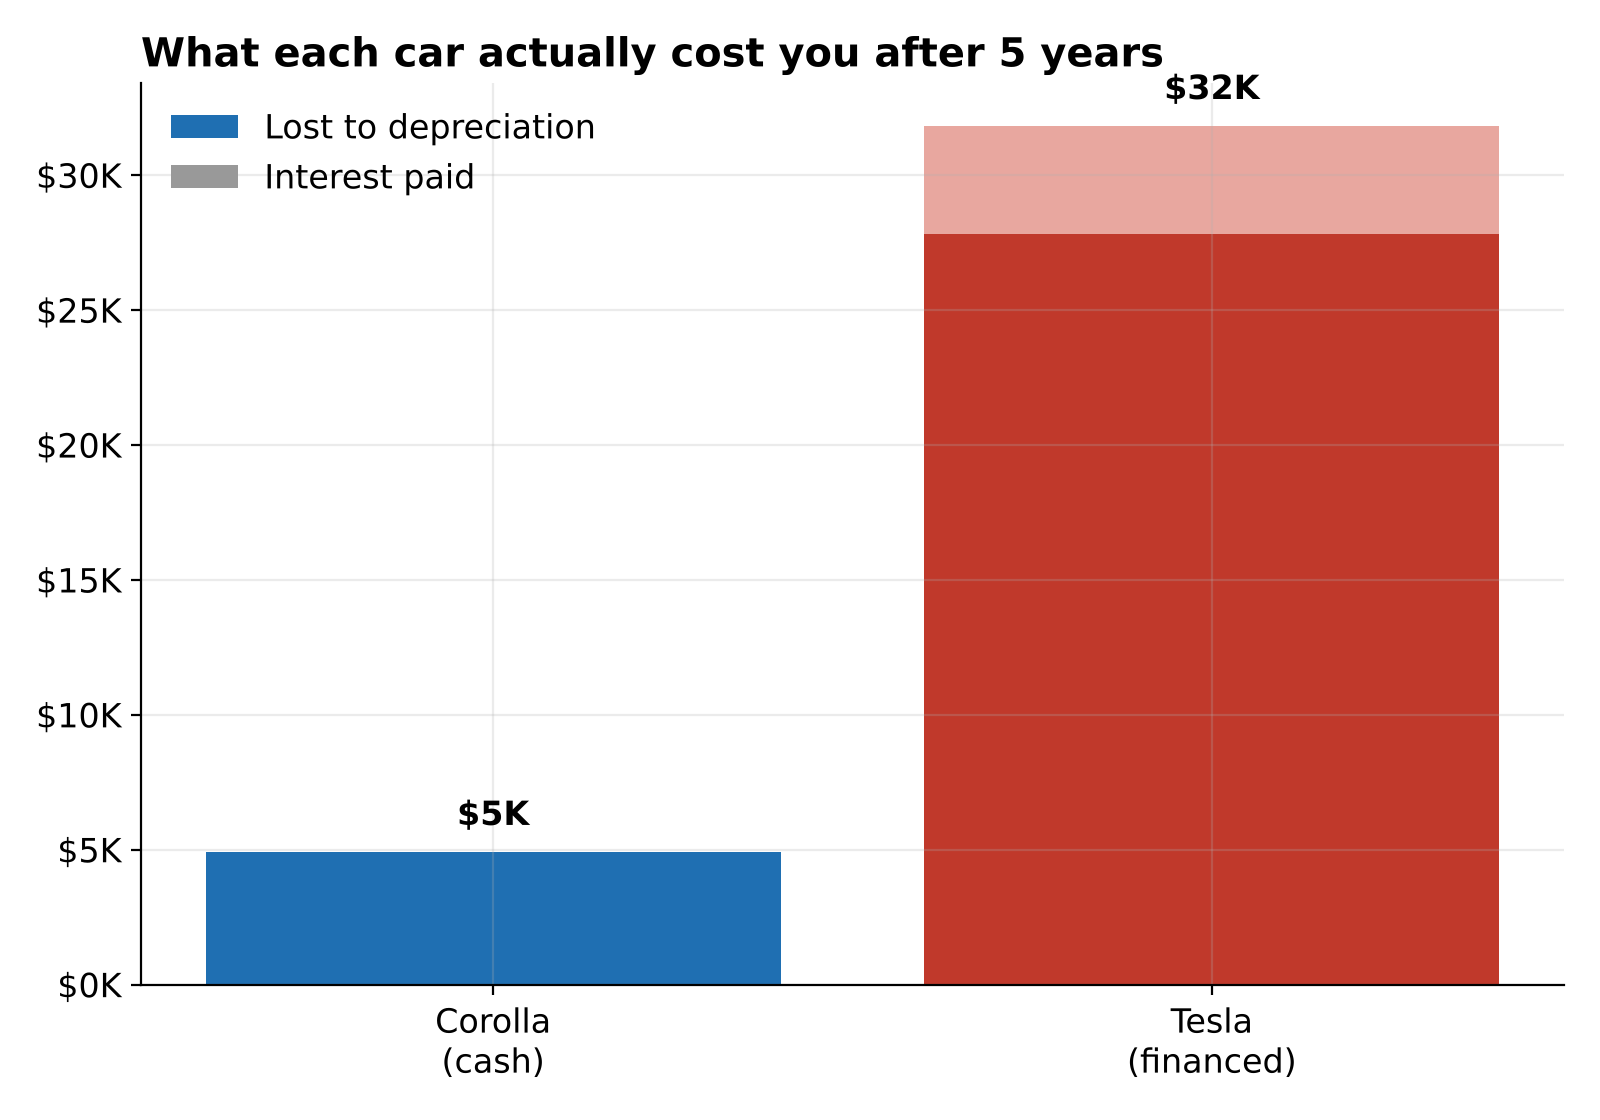
That’s a $27,000 gap, and it’s only year five. This is where most people stop doing the math. They think: “Okay, the Tesla costs more. But it’s a nicer car and I drive it every day.”
Fair…but let’s keep going.
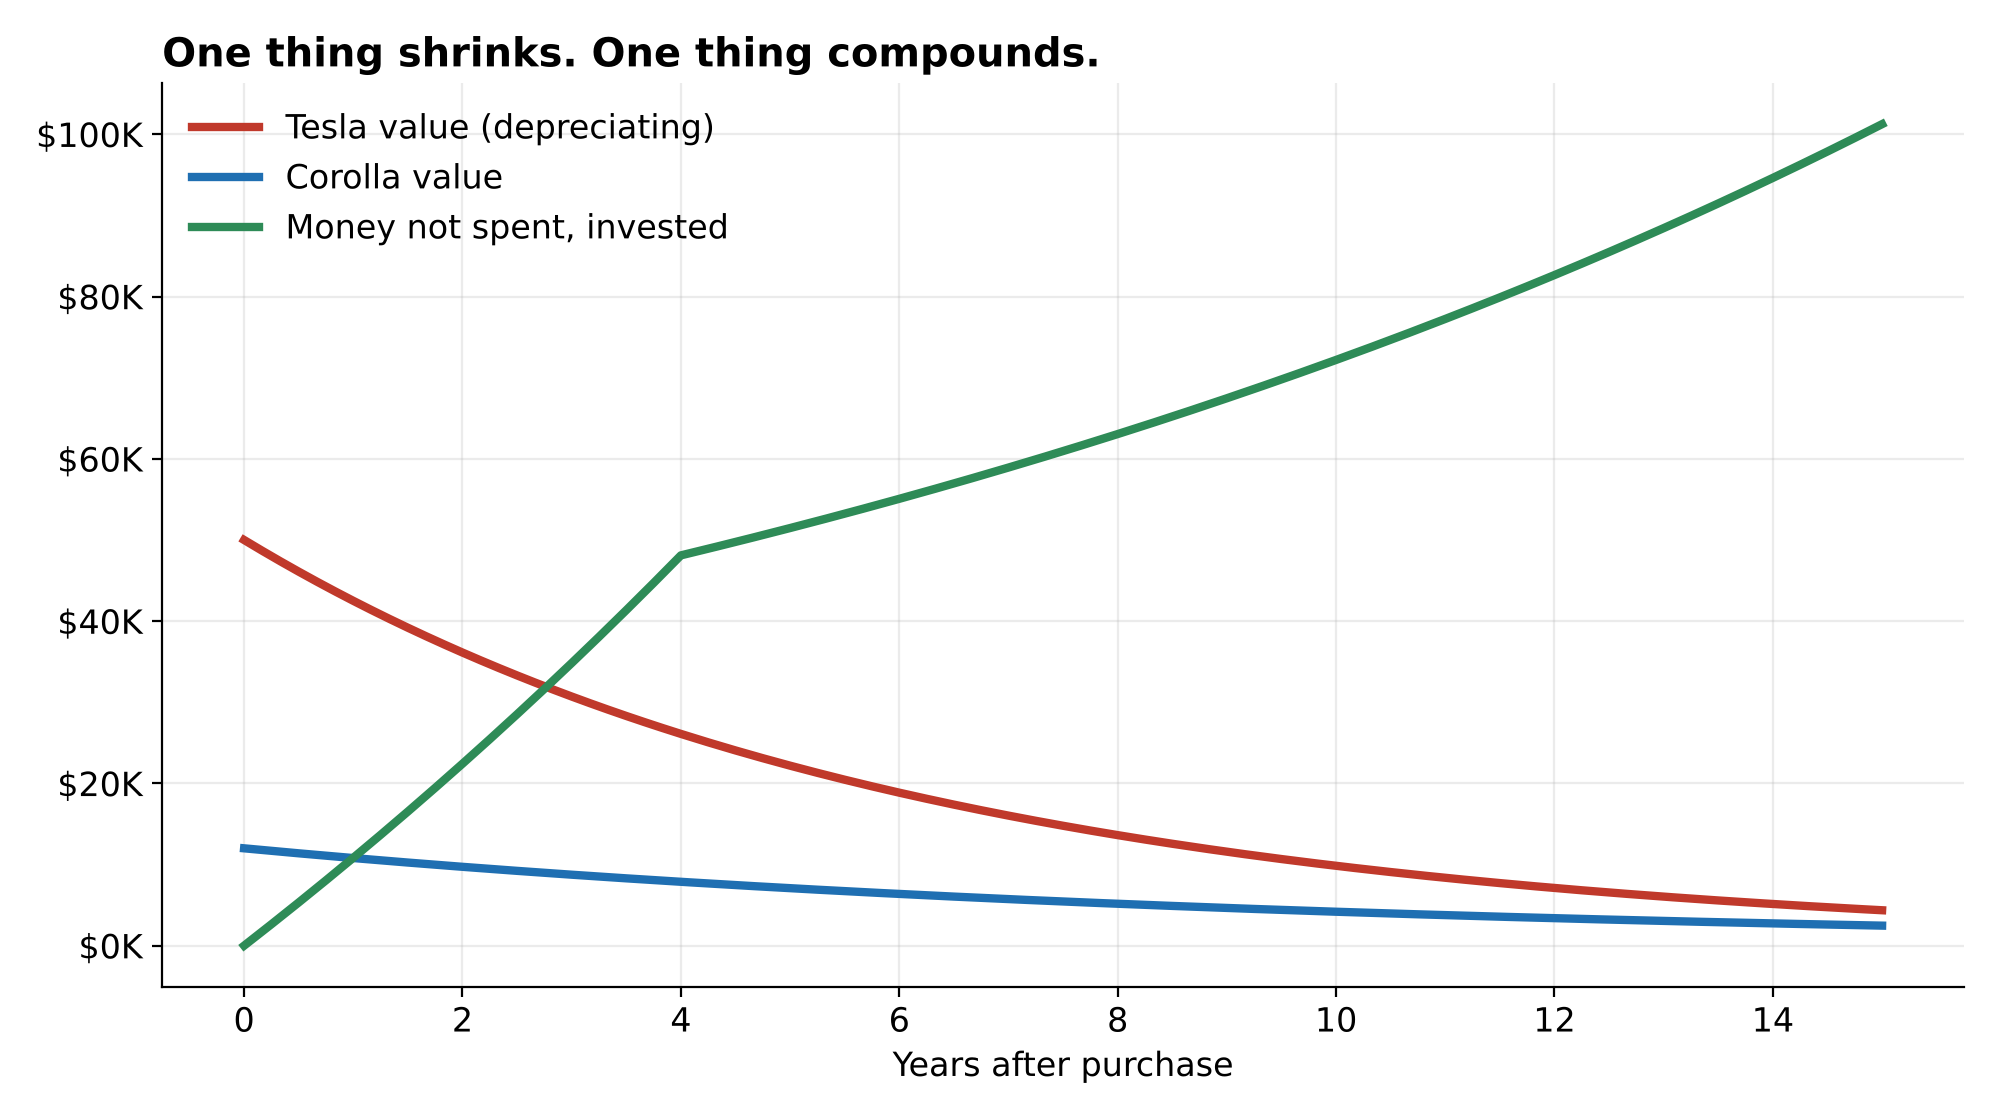
Here’s the picture that bothers me. One line is going down: the Model 3’s value, about $50,000 on day one and about $22,000 five years later. The other line is going up: the money that never got spent on it. Those lines cross in under three years. After that, it’s not even close.
Fifteen years later
At 37, the investing side of the ledger has grown to about $101,000. The Model 3, if he even still has it, is worth about $4,000. The net worth gap between us is roughly $99,000.
And then retirement
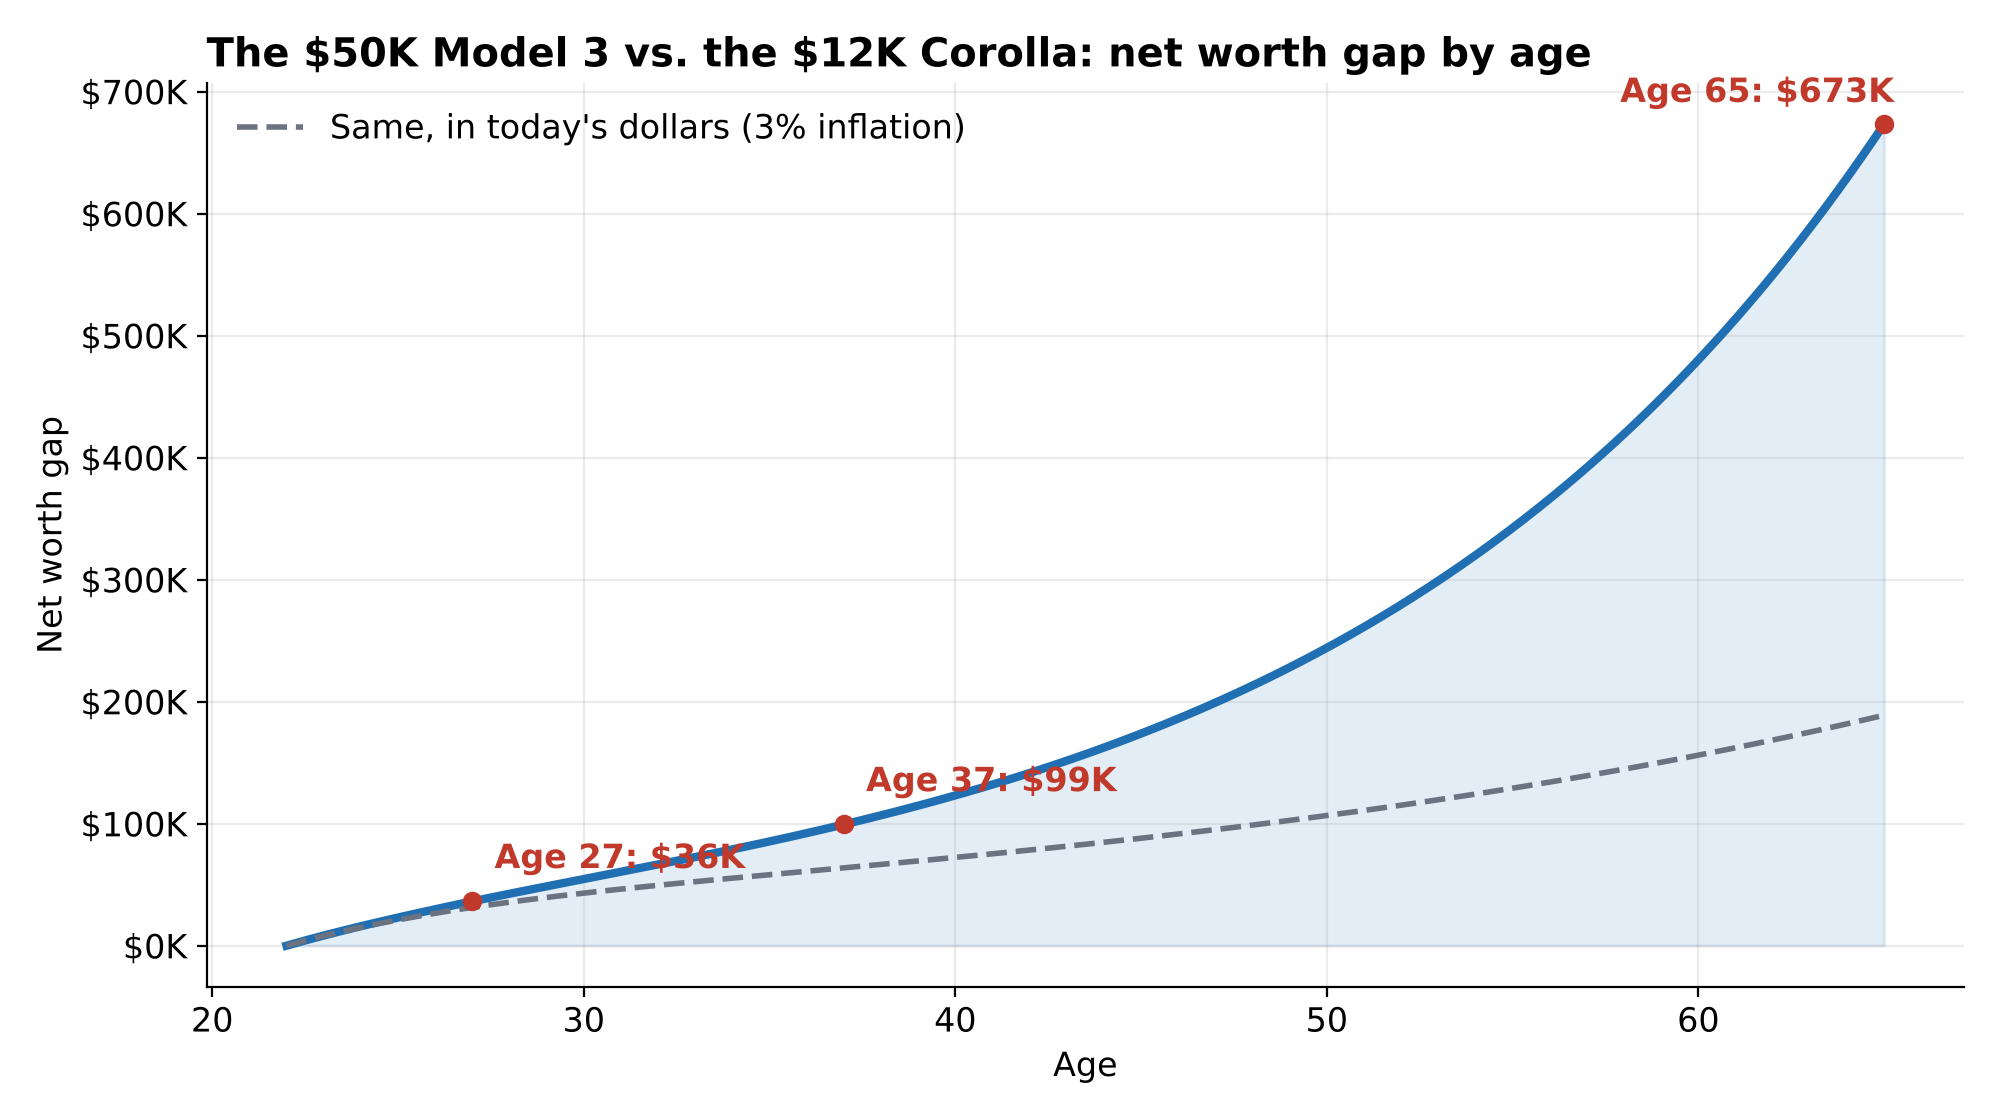
By age 65, that single decision is a gap of about $673,000. Adjusted for inflation, that’s roughly $190,000 in today’s dollars. That’s real money you never get back from a car that is worth nothing by then. And that is just for one car! Imagine repeating this process every 5-10 years!
Same job. Same salary. One of us bought a car. The other bought a car and a head start on retirement.
“But the Tesla owner invests too, right?” Absolutely, and he should. This isn’t about him being irresponsible. Every dollar that went into the car is a dollar that wasn’t invested. The gap is the opportunity cost: the difference between the money he has and the money he could have had.
It’s Not Just the Tesla
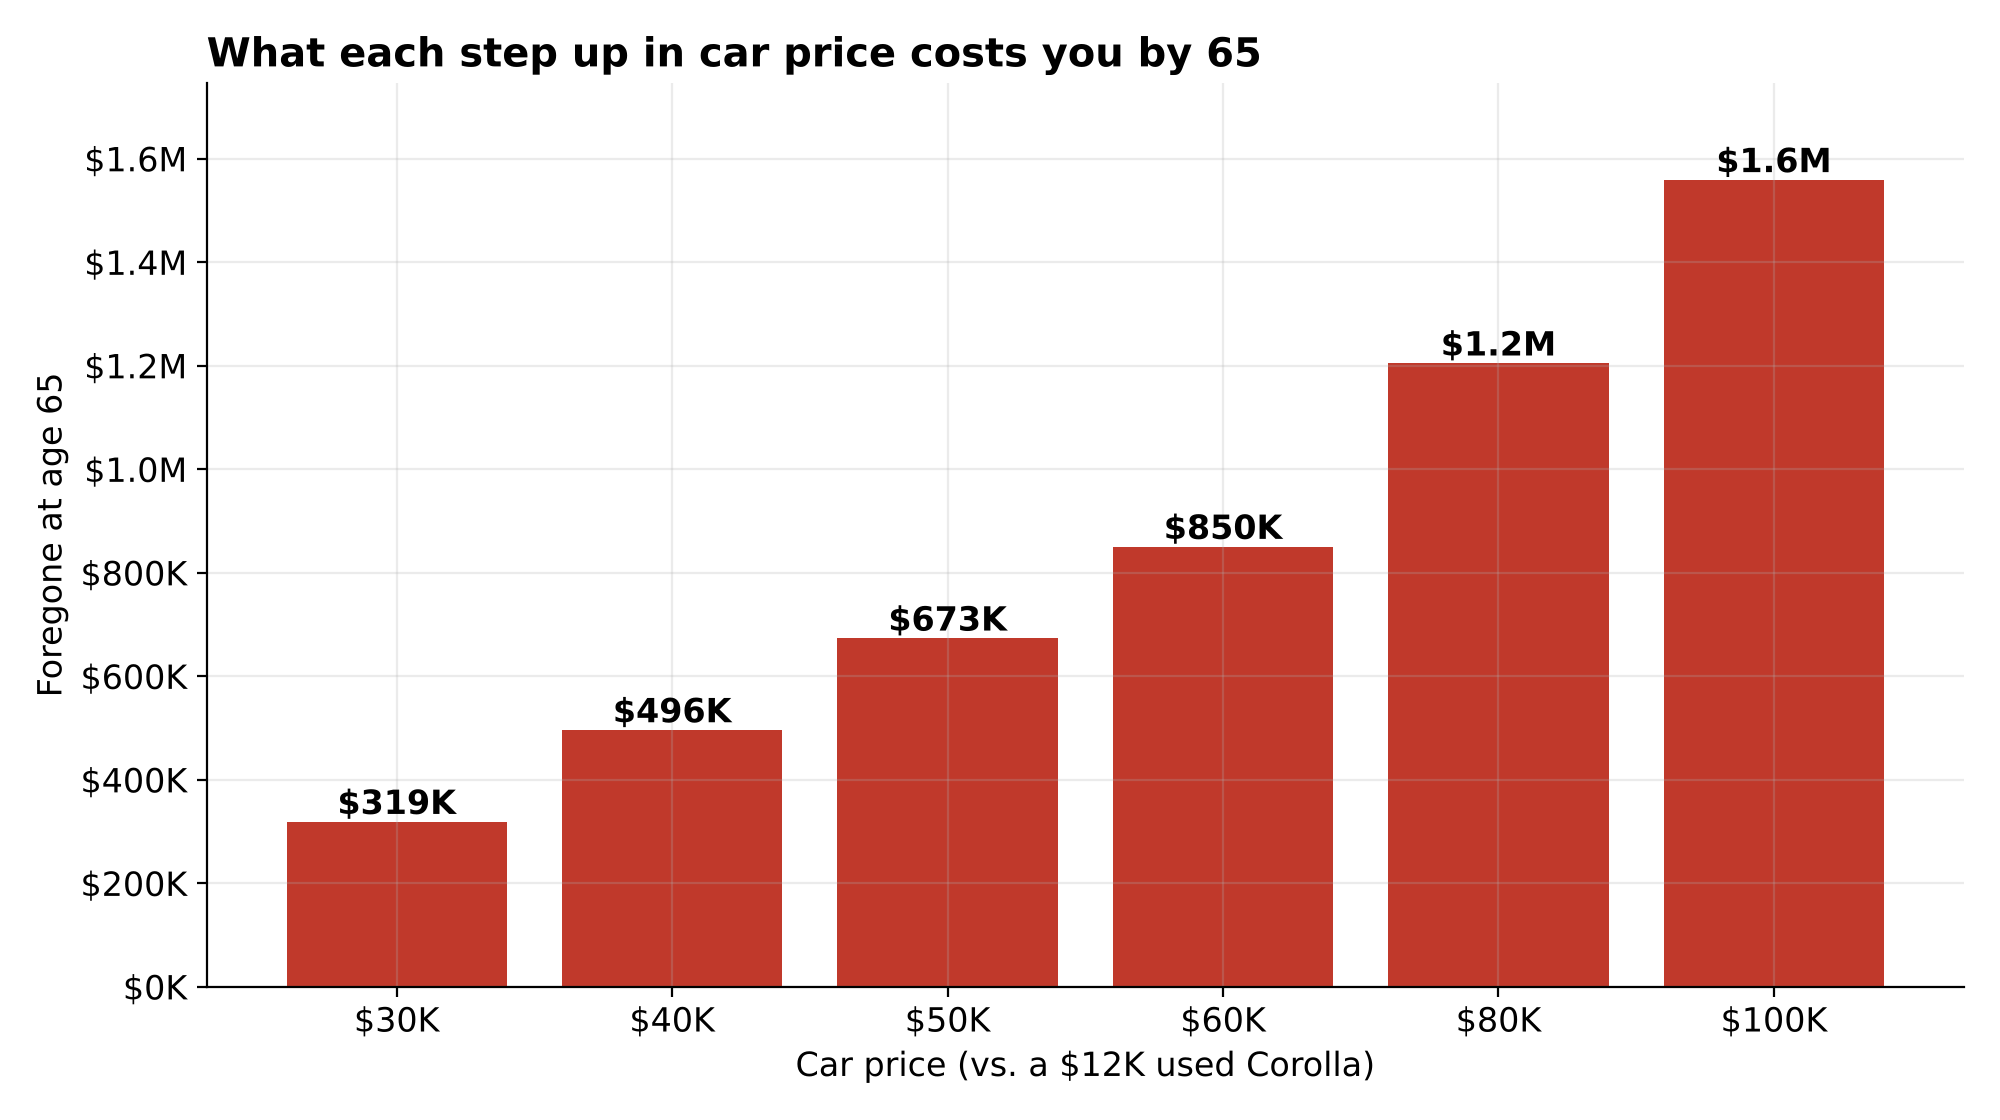
The Model 3 isn’t even the extreme case. Compared to the Corolla, a $30,000 car costs you about $319,000 by retirement. A $40,000 car, about $496,000. An $80,000 car? About $1.2 million. The cost scales with the price tag, but the real driver is when you do it.
The Real Lesson
This isn’t really a car story. Cars just happen to be the most common way people turn a big chunk of early income into a depreciating asset.
A depreciating asset loses value every year. The money you put into it is slowly, quietly disappearing. That applies to cars, boats, a lot of consumer tech, and high-end everything. Meanwhile, money invested early has the longest time to compound.
Here’s the part that matters most:
The money you earn in your early career is the most valuable money you will ever make.
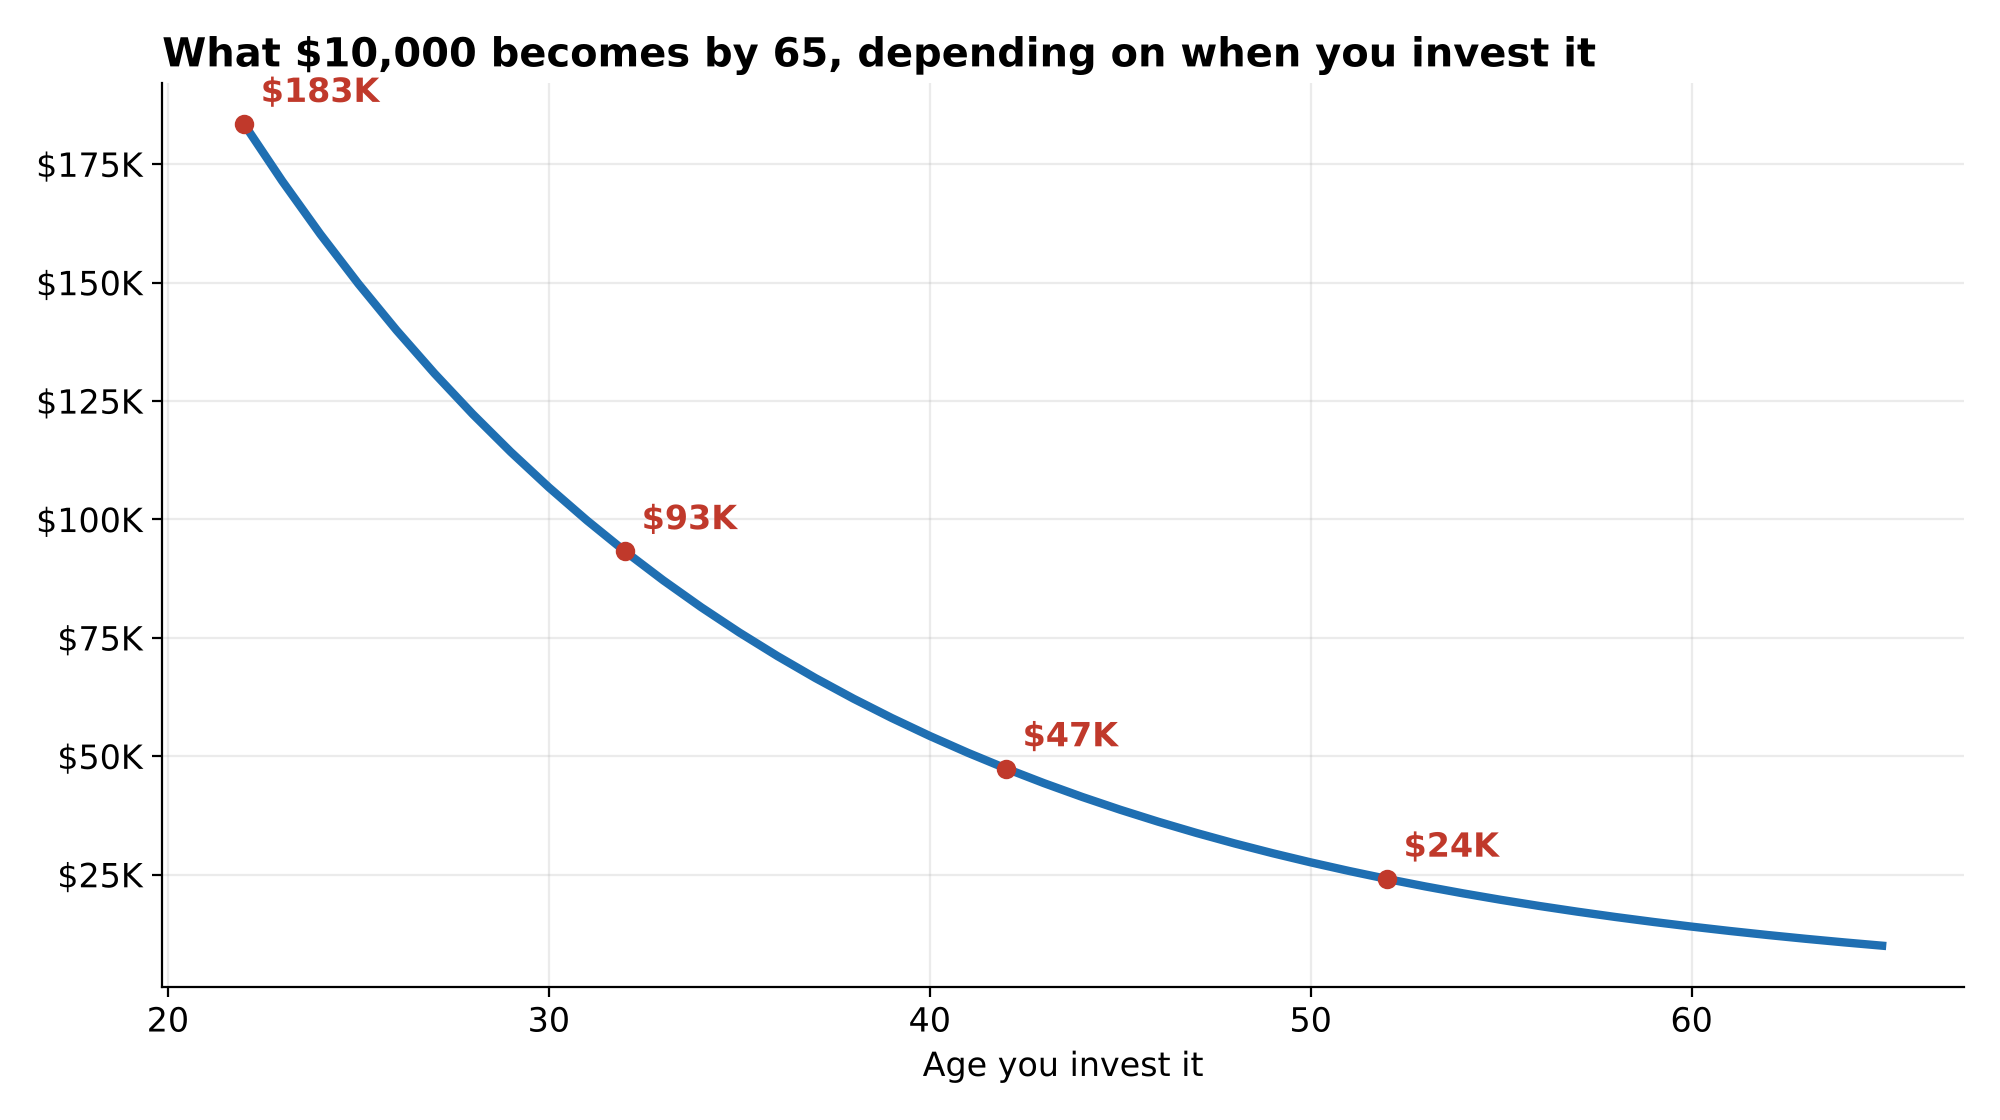
Not because it’s the biggest paycheck, but because it has 40+ years to work. $10,000 invested at 22 becomes about $183,000 by 65. That same $10,000 invested at 42 becomes about $47,000.
So what should you do?
I’m not telling you to live like a monk. I’m not telling you to drive a beater and eat rice forever. Reward yourself. Enjoy your money. You earned it.
But be deliberate. If you’re going to spend it, spend it on purpose, and know what it actually costs. Prioritize investing. Don’t put it off until “later.” Later is the most expensive time to start.
How I Calculated This
- Tesla price of $50k, approximately a 2021 Model 3 Long Range, before tax and fees.
- Loan: $12k down (equal to the Corolla’s cash price), $38k financed over 48 months at 5% APR.
- Depreciation: Tesla 15% per year, Corolla 10% per year (declining balance).
- Investing: 7% nominal annual return. The “today’s dollars” figure assumes 3% inflation.
- Not included: insurance, registration, fuel and maintenance differences (an EV may save on fuel and maintenance but typically costs more to insure), and replacing the cars later. Including them would shift the numbers somewhat in either direction.
- This is an illustration, not financial advice.